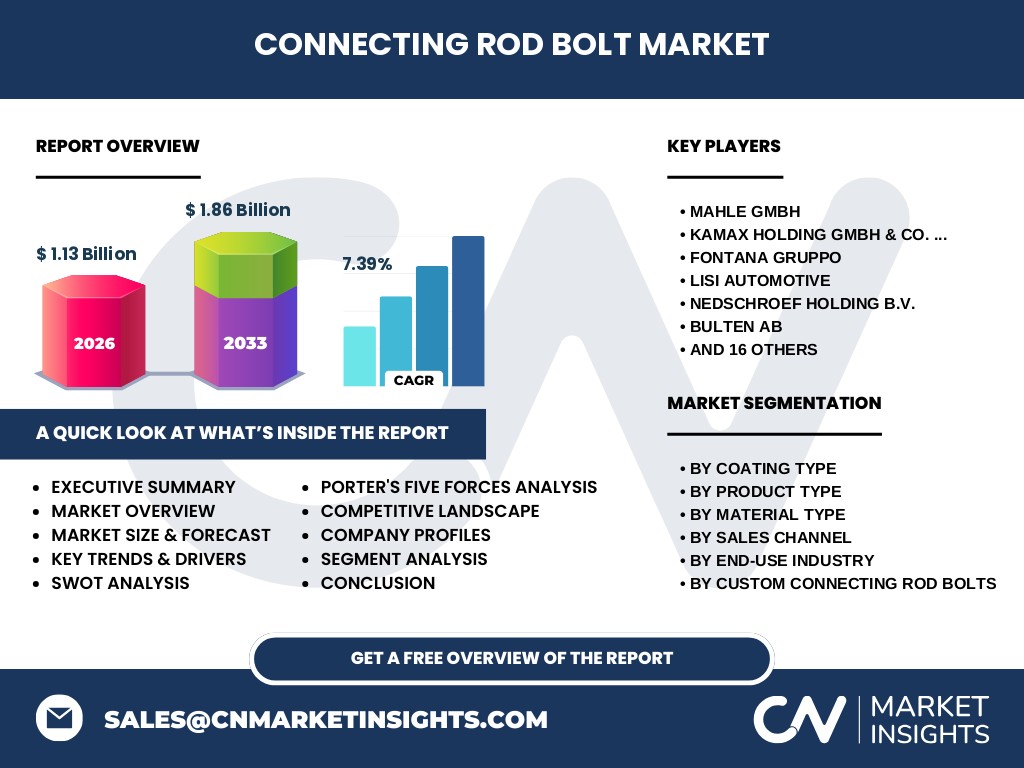
Market overview of the Connecting Rod Bolt Market
Our analysis indicates that the Connecting Rod Bolt Market is valued at 1.13 Billion in 2026. These precision fasteners secure internal combustion engine connecting rods under extreme cyclic tensile loads. Critical for automotive, marine, and aerospace sectors, industry significance stems from failure prevention in high-stress powertrains.
Key market drivers, restraints, challenges, and opportunities shaping the sector
Growth is driven by rising global vehicle production and heavy-duty industrial machinery expansion. However, strict ISO and SAE material regulations act as compliance hurdles. Opportunities lie in developing lightweight titanium and alloy steel fasteners to support fuel-efficient, high-performance powertrains globally.
Structural Growth Trends in Connecting Rod Bolt Market industry trends
The shift toward lightweighting and electrification creates a distinct bifurcation. While traditional internal combustion engine volumes plateau, demand for high-tensile Shot Peened Bolts and Torque To Yield Bolts accelerates within hybrid and high-performance racing segments requiring elite mechanical durability.
Pandemic impact analysis and recovery trajectory
COVID-19 severely disrupted global supply chains, causing raw material shortages in alloy and carbon steel sourcing. Recovery has been robust, propelled by aggressive backlog clearance in automotive manufacturing hubs across North America, Europe, and Asia-Pacific.
Competitive Benchmarking within the Connecting Rod Bolt Market market size
The market features high consolidation among Tier-1 suppliers like MAHLE GmbH, Kamax Holding GmbH & Co. KG, and Fontana Gruppo. Meanwhile, specialty performance brands such as Automotive Racing Products (ARP) dominate aftermarket racing channels through proprietary heat-treatment processes.
Executive summary of Connecting Rod Bolt Market analysis
Our research projects the Connecting Rod Bolt Market to expand from 1.13 Billion in 2026 to 1.86 Billion by 2033 at a CAGR of 7.39%. Strategic focus on advanced coating types and material customization will dictate long-term market leadership.
Projected growth trajectory from 2027 to 2033
Based on our econometric modeling, the market will scale steadily to reach 1.86 Billion by 2033, registering a robust CAGR of 7.39%. This expansion is underpinned by sustained industrial machinery demand and strict performance thresholds in aerospace engineering.
Segmentation analysis across product, material, coating, and end-use
The market bifurcates across Coating Type (Phosphate, Black Oxide, Zinc, Dry Film), Product Type (Standard, High-Performance, Custom), Material Type (Alloy, Carbon, Stainless Steel, Titanium), Sales Channel (OEM, Aftermarket), and End-Use Industry (Automotive, Marine, Aerospace, Industrial).
Geographic distribution and regional performance dynamics
Asia-Pacific leads consumption due to massive automotive manufacturing output in China, Japan, and India, supported by regional suppliers like Aoyama Seisakusho and Sundram Fasteners. North America and Europe follow closely, driven by heavy aerospace and high-performance aftermarket sectors.
In-depth regional review of manufacturing and supply hubs
Regional performance centers on major logistical corridors. European production relies on industrial clusters in Germany and Italy, featuring players like Pankl Racing Systems, while North American supply chains leverage specialized distribution networks centered around high-performance racing demands.
Strategic positioning of leading companies in the industry
Industry giants like Lisi Automotive and Nedschroef Holding focus on high-volume OEM contracts, whereas performance specialists such as CP-Carrillo and Eagle Specialty Products capture high-margin aftermarket segments with proprietary alloy formulations and specialized engineering.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to strict raw material specifications for alloy and titanium grades. Buyer power is high among major automotive OEMs, while threat of substitution is low given the specialized mechanical tolerances required for connecting rod applications.
SWOT evaluation of the Connecting Rod Bolt Market
Strengths include high tensile integrity and specialized coating innovations. Weaknesses involve vulnerability to raw material price volatility. Opportunities center on aerospace lightweighting, while threats include stringent environmental mandates impacting traditional manufacturing processes.
Value chain analysis from raw materials to end-users
Value flows from raw material extraction of alloy, carbon, and titanium stocks through precision forging and heat treatment by tier suppliers. Finished fasteners route through OEM assembly plants or global aftermarket distribution channels to reach end-users.
Investment insights and high-potential areas
Investors should target manufacturers specializing in Dry Film Lubricated coatings and titanium material types. These segments offer superior margins and align directly with lightweighting initiatives in the aerospace and high-performance automotive sectors.
Conclusion and core takeaways for stakeholders
The Connecting Rod Bolt Market offers compelling growth, projected to hit 1.86 Billion by 2033. Success requires aligning product portfolios with advanced material science and securing direct partnerships with tier-1 automotive and aerospace OEMs.
Research methodology and triangulation framework
Baseline estimates are triangulated by combining exhaustive trade registry data, primary stakeholder interviews with executives from firms like Bulten AB and SPS Technologies, and secondary macroeconomic indicators regarding global vehicle and industrial machinery production.
Scope of the report and coverage parameters
This report covers global market dynamics from 2026 to 2033, analyzing quantitative revenue figures alongside qualitative assessments of coating technologies, material breakdowns, and regional supply chain constraints across four primary end-use industries.
Recent developments, partnerships, and strategic moves
Recent industry activity highlights strategic acquisitions and capacity expansions by market leaders like MacLean-Fogg Component Solutions and Meidoh Co. Ltd., aimed at scaling production of advanced heat-treated and pre-lubricated fastening solutions for next-generation powertrains.